How dollar-cost averaging smooths out the risk of investing at the wrong time
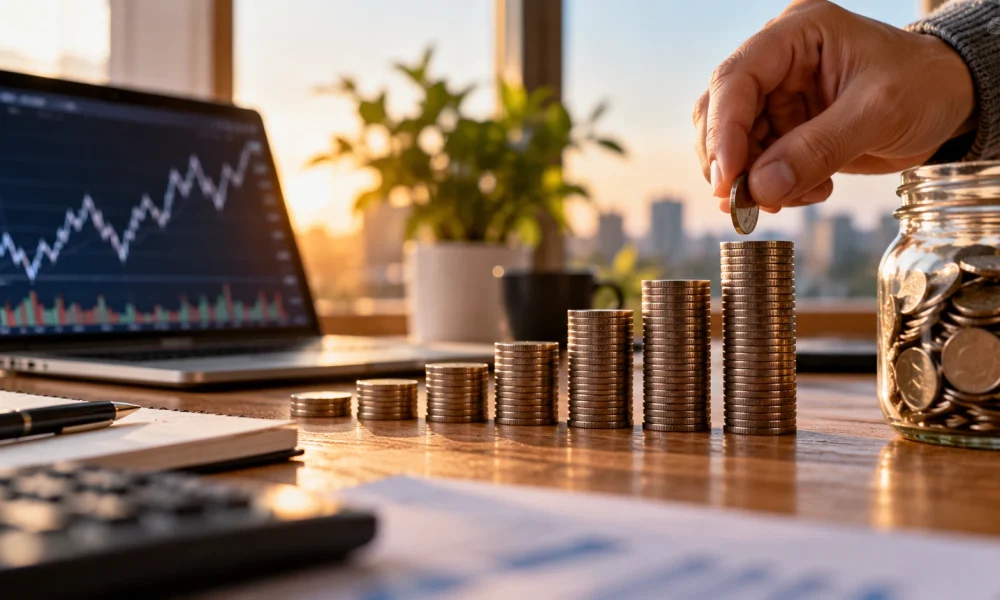
Dollar-cost averaging means investing a fixed amount at regular intervals, monthly for example, rather than investing a lump sum all at once. Its main benefit isn’t higher average returns; mathematically, investing a lump sum immediately tends to outperform dollar-cost averaging slightly more often than not, since markets trend upward over most long periods.
What dollar-cost averaging genuinely does well is reduce the emotional and psychological risk of investing, specifically the fear of putting a large sum in right before a downturn. Spreading purchases across many points in time means no single purchase is made entirely at the worst possible moment, which makes the approach easier for many investors to actually stick with consistently, compared to a lump sum that can trigger second-guessing if the market drops shortly after.
For most people contributing regularly from a paycheck, dollar-cost averaging isn’t really a deliberate strategy chosen over a lump sum alternative; it’s simply what happens naturally when a portion of every paycheck gets invested automatically, which is part of why it remains one of the most widely and successfully used approaches in practice, regardless of what the math says about lump-sum investing in isolation.
None of this is complicated once explained clearly, but it’s exactly the kind of detail that gets glossed over in most casual financial advice, which is part of why it trips people up in practice more often than the underlying concept really deserves.
Getting this right doesn’t require sophisticated tools or expert-level knowledge, just a bit of deliberate attention applied consistently over time, which tends to matter far more than most people assume in the moment.
It’s a small piece of financial literacy, but one that tends to compound in its own quiet way, shaping outcomes far more than its modest complexity would suggest.
In the end, small habits like this rarely feel urgent in the moment, but they’re exactly the kind of quiet groundwork that separates a stable financial picture years down the line from one that stumbles on something entirely avoidable.